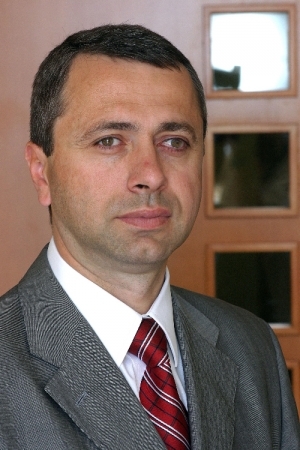
Despite the growth most global automotive production markets are experiencing and automotive supply assets that remain undervalued, merger and acquisition (M&A) activity is anticipated to decline by about 25 percent in 2013, with approximately 180 automotive supplier deals globally, according to PwC’s sixth annual Consolidation in the Global Automotive Supply Industry study. At the same time, the average deal size is likely to increase, driving the overall global deal value up to about $14 billion this year, substantially higher than in the previous two years. "Over the past 12 months, global automotive supplier M&A activity has slowed and that trend is expected to continue as European suppliers continue to be impacted by the debt crisis and the related low vehicle sales in Europe," said Ionuț Simion (photo), Tax Partner, Automotive Industry Leader, PwC Romania.
The study reveals that for the third consecutive year, European automotive suppliers are the key target of global automotive supplier M&A activity, and the top buyers are large North American suppliers.
PwC’s study also reveals that the strongest growing suppliers in 2012 were South Korean companies, with a combined average growth rate of almost 20 percent in the past year for the 46 largest South Korean suppliers, while Japanese suppliers declined at a rate of about five percent in the same period. Chinese suppliers’ profitability declined by 19 percent, as they likely underestimated the slowing of the growth curve in China automobile production.
PwC’s 2013 list of the top 10 potential consolidators within PwC’s Global 100 suppliers showcases six North America companies and only three European and one Chinese. The top 10 consolidators executed on average 11 acquisitions each in the past five years. Each of the most likely consolidators has been evaluated on their "buyer score," a measure of their financial and operational ability to acquire other suppliers, as well as on their "buyer attitude," a measure of their willingness to make acquisitions.
For more details about the Consolidation in the Global Automotive Supply Industry Study, download the publication at: www.pwc.com/auto.
About the Study
The sixth annual Consolidation in the Global Automotive Supply Industry 2013 Study evaluates the largest automotive suppliers worldwide with respect to financial and operational performance and acquisition history. The expanded 2013 study includes 775 automotive suppliers with aggregate revenues of approximately US$3 trillion in 2012, from Brazil, China, Europe, India, North America, Japan, and South Korea. The annual study is developed by PwC’s Global Automotive Management Consulting practice.
About PwC's Automotive Practice
PwC's global automotive practice leverages its extensive experience in the industry to help companies solve complex business challenges with efficiency and quality. One of PwC's global automotive practice's key competitive advantages is Autofacts®, a team of automotive industry specialists dedicated to on-going analysis of sector trends. Autofacts provides our team of more than 4,800 automotive professionals and our clients with data and analysis about automotive production and capacity to assess implications make recommendations, and support decisions to compete in the global marketplace.
About PwC
PwC helps organisations and individuals create the value they’re looking for. We’re a network of firms in 158 countries with more than 180,000 people who are committed to delivering quality in assurance, tax and advisory services. Tell us what matters to you and find out more by visiting us at www.pwc.com/ro